Property Cashback
in Malaysia.
Understand the property.
Understand the financing.
Understand your cashback.
A property purchase is a big financial decision. So when a property comes with cashback, the first question should not be just “How much cashback can I get?”
Know what you are buying, how much you need to borrow, your monthly payment and how the cashback works. At Citi Harta Tanah, we help you look at the full picture before you decide.
Property selection
Understand the actual property you are buying.
Financing guidance
Know your estimated loan and monthly repayment.
Clear transaction terms
Understand the cashback conditions and purchase documents.
What exactly is
property cashback?
Think of it as buying a property that comes with an additional financial incentive. Some selected transactions may include cashback or a rebate from the developer or seller, depending on the property and agreed terms.
You are still buying an actual property through a legal transaction. If you use bank financing, you still have a housing loan to repay. The cashback is a separate part of the transaction that needs to be explained and properly documented.
An incentive may reduce the effective property cost or involve a separately documented payment. The amount, timing and treatment must be compatible with the financing requirements and legal documents.
Four parts to understand
- 01
The property
What you are buying and its actual purchase price.
- 02
The agreement
The purchase terms, costs and incentive in writing.
- 03
Bank financing
The approved loan, repayment and bank conditions.
- 04
Potential cashback
How the benefit is applied, and when it is due.
These are parts of the same transaction, not a promise of approval or payment.
Found a property you like?
Ask these five questions first.
- What is the actual purchase price?
- How much financing can the bank approve?
- What cashback or rebate is documented?
- How much money must I prepare?
- What will I pay every month?
“Don’t buy a property just because the cashback looks attractive. Buy because the entire transaction makes sense for you.”
A simple property
cashback example.
The property price, potential cashback and monthly loan payment are different numbers. Keep them separate.
Illustrative condominium exampleThe loan assumptions
- Annual interest rate
- 4.0%
- Loan tenure
- 35 years
- Loan amount
- RM400,000
All figures are hypothetical and used for education only. The photograph does not represent an RM500,000 offer.
The example price stated for the property.
A possible transaction incentive, not an extra bank loan or guaranteed cash in your account.
The loan to repay in this example. This is a separate assumption, not “price minus cashback”.
Based on RM400,000 over 35 years at 4.0% a year.
How the incentive is treated matters
The benefit depends on how it is documented and applied. A reduction, rebate or payment needs to be disclosed and treated appropriately in the financing and legal arrangements.
The loan is an illustration, not an entitlement
A bank may assess the property price, net consideration after incentives, valuation and your eligibility differently. Actual approval may be higher or lower. Rates and repayments may change with the financing product.
What if you rent it out?
Assume you receive RM1,600 in rent each month.
You would need about RM171 more each month, before other property expenses. Maintenance, repairs, insurance, taxes, vacancies and other costs can increase the amount you need to pay.
One is a potential transaction benefit. The other is money you may receive from a tenant each month. Do not combine them when calculating monthly rental cash flow.
A good cashback offer must also
be a good property deal.
Cashback can catch your attention. The property itself should still meet your needs. Here are four things we encourage buyers to check.
Would you still want it without the cashback?
Look at the location, condition, nearby facilities and access. Think about whether it suits your own stay or rental plans. A cashback offer cannot make an unsuitable property right for you.
Can you afford it when there is no tenant?
Work out the repayment alongside your existing commitments. Allow for maintenance, repairs, insurance, taxes and empty months. Do not rely on cashback to cover a long-term shortfall.
What exactly will you receive, and when?
Ask who provides the incentive, how it is documented, what conditions apply and when it is due. Check how it is reflected in the purchase price, bank financing and legal documents.
What must you pay before completion?
Ask for a written breakdown of the deposit, legal fees, duties, financing costs and other charges. Find out which amounts you must pay first. Cashback does not automatically remove these costs.
We walk through
the details with you.
Citi Harta Tanah helps you understand the property and transaction. You should have time to ask questions before deciding.
- 01
Tell us your plans
Let us know your budget, commitments and whether you want to live in the property or rent it out.
- 02
Look at suitable properties
We discuss the location, price, condition and available information. Ask for a viewing and confirm current availability.
- 03
Discuss the financing
We explain the information needed for an initial eligibility discussion. The bank carries out its own assessment and decides whether to lend.
- 04
Review the documents
Check the purchase price, incentive, costs and conditions with the relevant bank and legal professionals before committing.
- 05
Complete and plan ahead
Complete the required purchase and financing steps. Any cashback follows its documented conditions and timing. Plan for repayments and ongoing ownership costs.
Start with a property.
Then check the details.
These listings are separate from the hypothetical example above. Confirm the current price, availability and incentive terms with our team.
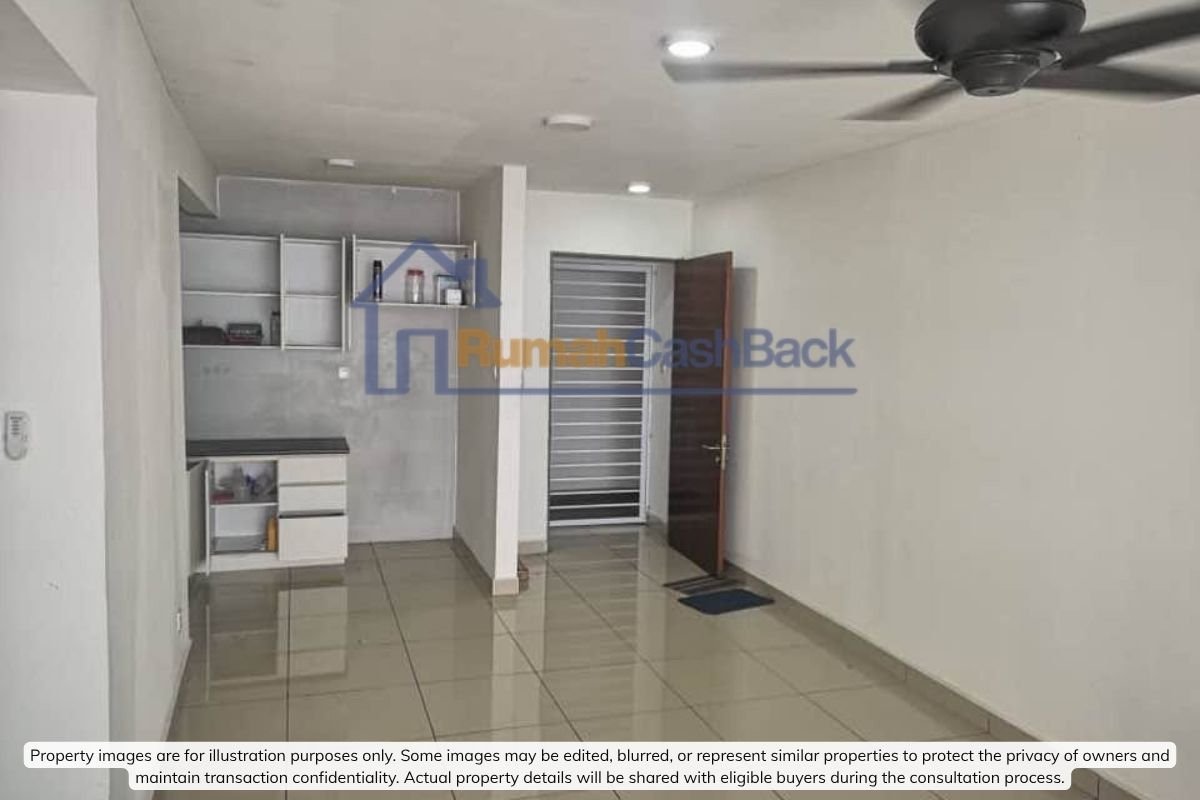 Freehold · Subsale
Apartment in Subang Jaya
Subang Jaya
3 beds · 2 baths · 1150 sq.ft.
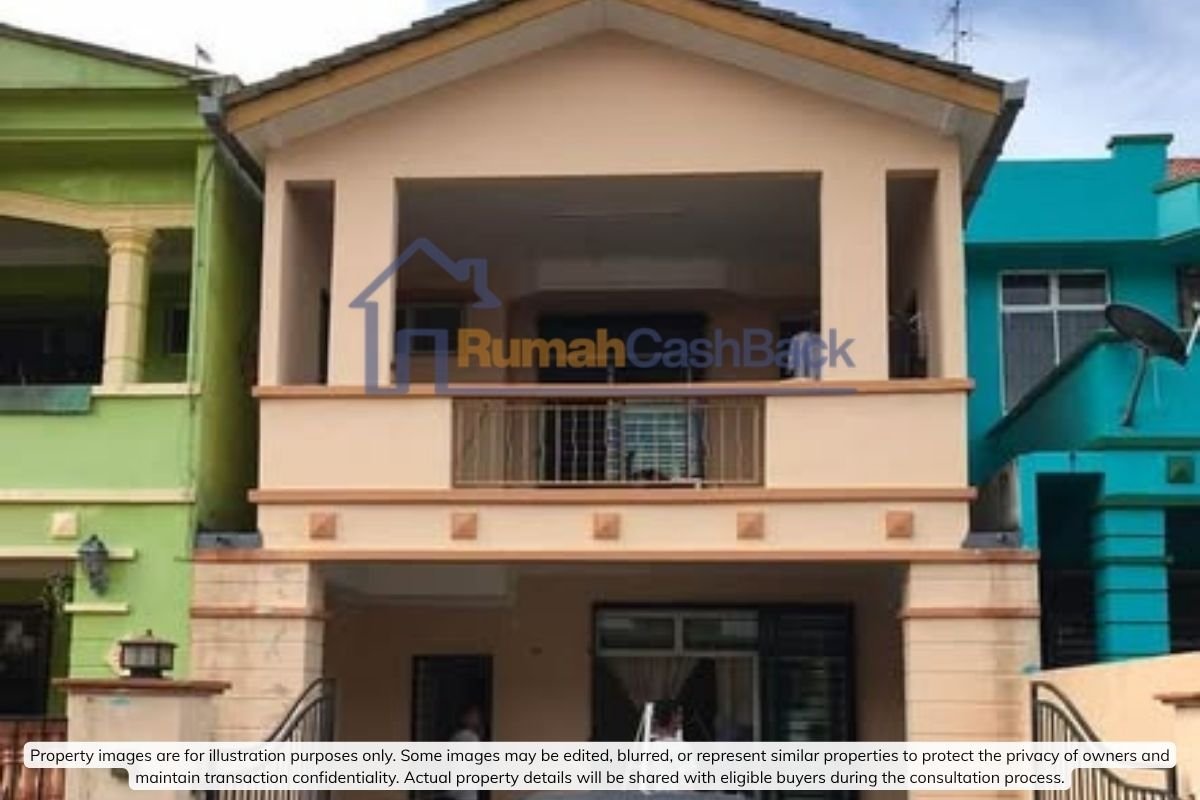 Freehold · Subsale
Landed home in Serdang
Serdang
4 beds · 3 baths · 2470 sq.ft.
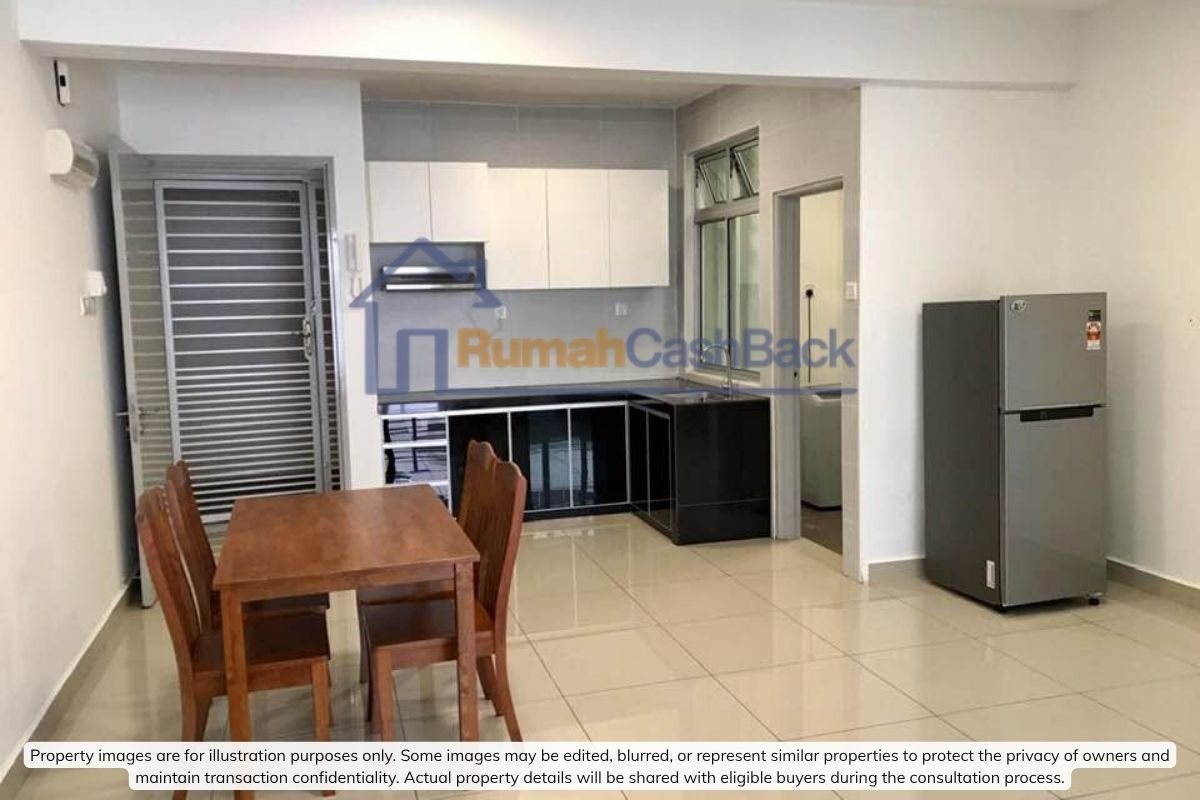 Freehold · Subsale
Condominium in Cyberjaya
Cyberjaya
2 beds · 2 baths · 950 sq.ft.
Before you
go any further.
You do not need to know all the property terms before speaking with us. Start with the questions that matter to you.
Ask our teamWill everyone qualify for a cashback property?
No. The property, transaction terms and your financial position all matter. An initial discussion is not a loan approval. The bank makes its own decision.
Does cashback mean I can buy with no money upfront?
No. You may still need money for a deposit, legal fees, duties and other charges. Ask for the full cost breakdown and payment dates for the specific property.
Who pays the cashback, and when will I receive it?
It depends on the arrangement with the developer or seller. Ask for the amount, payer, conditions and timing in writing. Do not assume that loan approval alone triggers payment.
Why must the bank know about the incentive?
The financing needs to be assessed using the actual transaction details. Ask the bank and your lawyer how the incentive should be disclosed and reflected in the documents. Do not leave it out or rely on an informal side promise.
Can the cashback cover my monthly loan repayments?
A transaction incentive is different from recurring income. Even if you receive cash, the housing loan continues. Assess whether you can afford the repayments and other costs over time.
What if the rent is lower than my repayment?
You need to pay the difference from your own money, plus any other expenses. Allow for empty months and repair costs too. Rent and occupancy are not guaranteed.
Is this the same as refinancing my current home?
No. This page explains buying a property with a possible incentive. Refinancing involves replacing financing on a property you already own.
What should I prepare for a first discussion?
Start with your preferred area, budget, intended use and questions. Our team will explain what information may be needed next. Send personal documents only through an agreed channel.